10xTravel is part of an affiliate sales network and receives compensation for sending traffic to partner sites, such as CreditCards.com. This site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened. This compensation may impact how and where links appear on this site. This site does not include all financial companies or all available financial offers. Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. All values of Membership Rewards are assigned based on the assumption, experience and opinions of the 10xTravel team and represent an estimate and not an actual value of points. Estimated value is not a fixed value and may not be the typical value enjoyed by card members.
Tracy Nylander has worked in real estate for 23 years through Nylander Group, buying and selling homes while more recently expanding into rental-property investing.
Her typical business spending ranges from roughly $1,000 to $5,000 per month, with construction materials and gas accounting for much of it. That spending alone doesn’t necessarily make it easy to meet the requirements on some of the largest business credit card welcome offers. A house flip, however, presented a different opportunity.
Timing a Business Card With a Major Project
When Nylander knew she had significant renovation expenses coming, she opened The Business Platinum Card® from American Express.
The house flip created a temporary increase in legitimate business expenses, allowing her to put renovation costs toward the card’s minimum spending requirement in order to earn the welcome offer.
That timing was important. Instead of opening a card and then looking for ways to meet a large spending requirement, Nylander matched the application to a period when she already knew the business would be spending more than usual.
When she isn’t working toward a welcome offer, Nylander estimates that her regular business expenses generate roughly 3,000 transferable points per month.
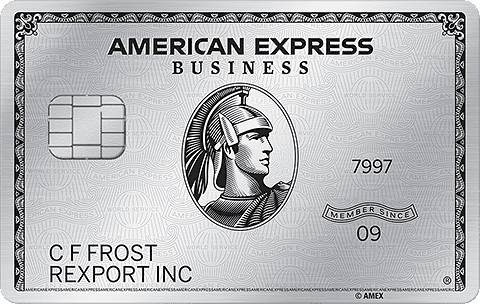
The Business Platinum Card® from American Express
You may be eligible for as high as 300,000
Membership Rewards® points
after spending $20,000 in eligible purchases on your new Card in your first 3 months of Membership. Welcome offers vary and you may not be eligible for an offer. Learn more.
Annual Fee:
$895
Turning Real Estate Expenses Into Memorable Trips
The rewards earned through business cards have helped Nylander book several significant trips.
One of her favorite redemptions was a week at Secrets Akumal booked entirely with points. She and her partner are also scheduled to fly Japan Airlines business class, an experience she says wouldn’t have been possible without the welcome offers she earned from business credit cards.
For a business that doesn’t consistently generate massive monthly expenses, welcome offers have played an important role in accelerating her points balance.
Rethinking the Strategy After the Welcome Offer
After roughly two years of pursuing credit card bonuses, Nylander has started thinking more carefully about her long-term card strategy.
Application velocity has become more of a constraint, making it increasingly important to consider which cards deserve a permanent place in her wallet rather than focusing exclusively on the next welcome offer.
She also wishes she had understood earlier which cards earned the most rewards in the spending categories that matter to her business and planned the order of her applications accordingly.
Advice for Business Owners With Irregular Spending
Nylander’s experience provides a useful blueprint for businesses with expenses that fluctuate substantially throughout the year.
Real estate investors may have renovations or property improvements. Retailers may place large seasonal inventory orders. Other businesses may periodically purchase equipment or make significant investments in growth.
When those expenses are predictable, they can provide a natural opportunity to pursue a business credit card welcome offer without increasing spending simply to earn a bonus.
The Bottom Line
Nylander’s strategy shows why the timing of a business credit card application can matter almost as much as the card itself.
A business owner who normally spends a few thousand dollars per month may have difficulty meeting a large spending requirement. Pairing the application with an already-planned project can change the equation completely.
For Nylander, renovation expenses that were necessary to complete a real estate project also helped generate rewards that have since opened the door to resort stays and international business class travel, all on points.
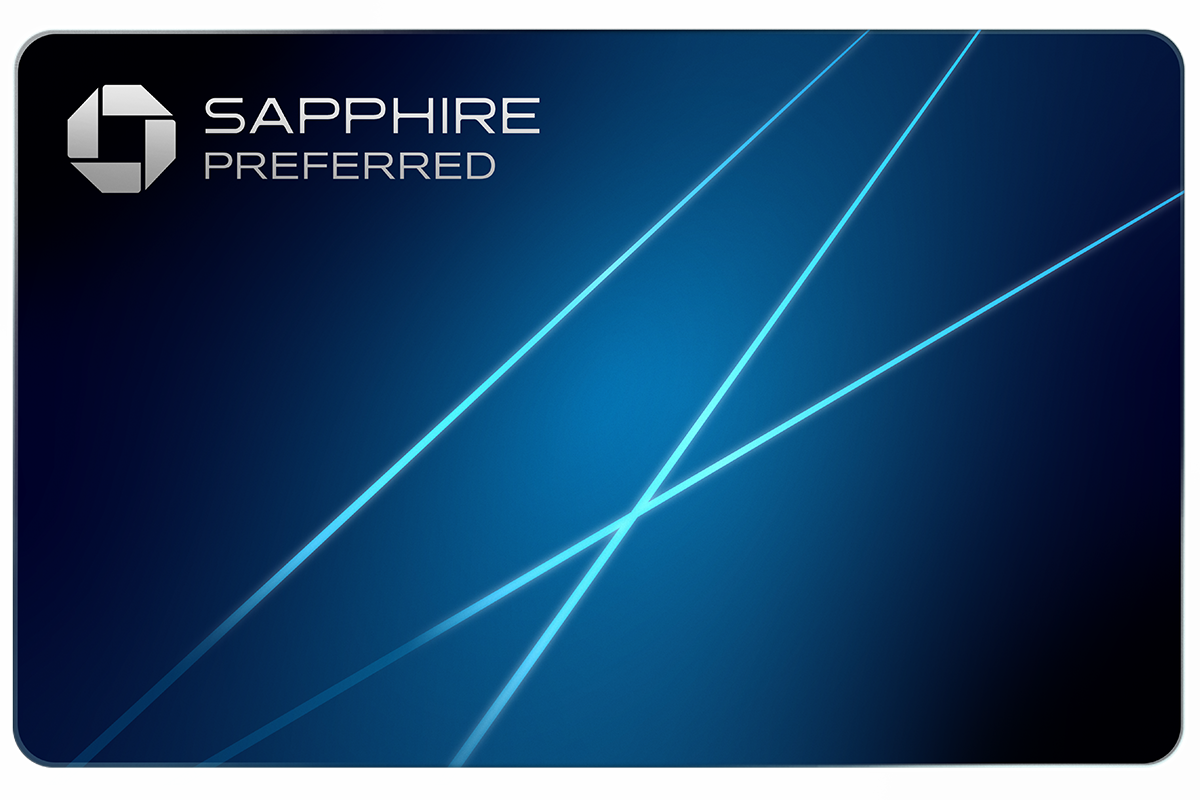
New to the world of points and miles? The Chase Sapphire Preferred® Card is the best card to start with.
With a bonus of Earn 75,000 bonus points after you spend $5,000 on purchases in the first 3 months from account opening. , 5x points on travel booked through the Chase TravelSM Portal and 3x points on restaurants, streaming services, and online groceries (excluding Target, Walmart, and wholesale clubs), this card truly cannot be beat for getting started!
after spending $20,000 in eligible purchases on your new Card in your first 3 months of Membership. Welcome offers vary and you may not be eligible for an offer. Learn more.
Annual Fee:
$895
Editors Note: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, hotel, airline, or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included within the post.
10xTravel is part of an affiliate sales network and receives compensation for sending traffic to partner sites, such as CreditCards.com. This site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened. This compensation may impact how and where links appear on this site. This site does not include all financial companies or all available financial offers. Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. All values of Membership Rewards are assigned based on the assumption, experience and opinions of the 10xTravel team and represent an estimate and not an actual value of points. Estimated value is not a fixed value and may not be the typical value enjoyed by card members.
Editors Note: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, hotel, airline, or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included within the post.
bonus cash back
after you spend $6,000 on purchases in the first 3 months from account opening.
earn 75K bonus miles miles
once you spend $4,000 on purchases within 3 months from account opening.
bonus points
after you spend $5,000 on purchases in the first 3 months from account opening.
Membership Rewards® Points
after you spend $8,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Welcome offers vary and you may not be eligible for an offer. Apply to know if you’re approved and find out your exact welcome offer amount – all with no credit score impact. If you’re approved and choose to accept the Card, your score may be impacted.