10xTravel is part of an affiliate sales network and receives compensation for sending traffic to partner sites, such as CreditCards.com. This site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened. This compensation may impact how and where links appear on this site. This site does not include all financial companies or all available financial offers. Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. All values of Membership Rewards are assigned based on the assumption, experience and opinions of the 10xTravel team and represent an estimate and not an actual value of points. Estimated value is not a fixed value and may not be the typical value enjoyed by card members.
Today we’re making a big change to our card recommendations, particularly for those newer to points and miles, and we felt a change like this deserved some explanation. We are now recommending that beginners start with the Capital One Venture Rewards Credit Card. This is replacing our longstanding recommendation of starting with the Chase Sapphire Preferred® Card. You’ll soon notice these changes inside the course, the personalized card rankings inside of My10x, and elsewhere.
Our advice is changing because it is now our opinion that the opportunity cost of pursuing Chase cards before Capital One is more of a blocker to your points strategy than the opposite.
There are five main reasons driving this change:
- Chase updated their bonus restrictions to once per lifetime.
- 5/24 is less of an issue than it used to be.
- Capital One is more inquiry sensitive.
- Capital One Venture family restrictions make order matter.
- Capital One’s simplicity makes it more beginner friendly.
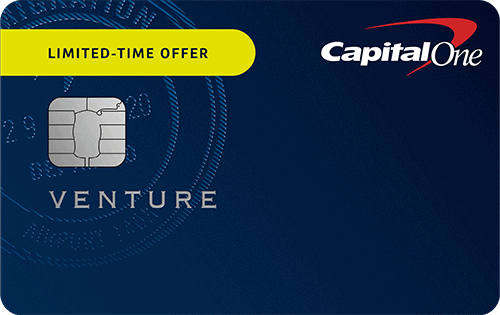
Capital One Venture Rewards Credit Card
Limited Time Offer: Enjoy a $300 stays credit, plus
earn 75K bonus miles miles
once you spend $4,000 on purchases within 3 months from account opening.
Annual Fee: $95
Chase’s Lifetime Restrictions Means You Should Wait for an Elevated Offer
This is what really started the conversation – is the Chase Sapphire Preferred still the best card for us to recommend to newbies to points and miles? When you could previously earn the bonus on the CSP every 48 months (and 24 months before that), our advice was to not wait for a higher offer. The opportunity cost of 25,000 or 40,000 points wasn’t worth not getting your clock started.
If you wait a year for a higher offer of say, 100,000 points on a card where you can get the bonus every 48 months, that means that your earning potential over 5 years is 100,000 points.
If the offer is 60,000 but you get it immediately, then in that same 5-year window you would be able to get it again. Even at that repeat point, if it is worth only 60,000 points, then the earning potential for that card is 120,000 points.
It was clear – waiting for an optimum time reduces your potential points earnings over the same window.
With the new lifetime restrictions, the math doesn’t hold up anymore. The windows are gone because you’re eligible for one bonus per lifetime on that product. Because of that, it now does make sense to wait for an elevated offer window. Especially given that one seems to come around at least once a year.
An elevated offer isn’t guaranteed to continue, but with the info available right now, the advice simply should be to hold off. The CSP is still a card you should get early on, but you should wait until you get a limited-time offer in your first 12-18 month window, which is fairly likely.
Family Restrictions on Chase Ink® Cards Make 5/24 Less of an Urgency
Chase Ink® cards don’t count toward your 5/24 count, but Chase won’t approve you for one unless you are under it. That’s just as true now as it was 1 to 2 years ago. Before the Ink restrictions were in place, you could keep cycling Ink cards. Staying under 5/24 meant you could keep getting Inks virtually indefinitely without adding to your 5/24 count because you could earn the bonus on the Chase Ink Business Cash® Card and the Chase Ink Business Unlimited® Card at least every 24 months.
With the family restrictions in place, this changes a recurring opportunity into a one-time payout. Previously, going over 5/24 didn’t just cost you a few cards, it shut off one of the single most reliable sources of Ultimate Rewards for as long as you remained over 5/24. That’s why starting with Chase and protecting your 5/24 slots was good advice. Go over and you just shut off a faucet.
Now, Chase treats the Ink Cash and Ink Unlimited as one family. You can earn one bonus between the two cards once per lifetime. Starting early no longer buys you a second or third or fourth round. Chase shut off the stream for you. This means staying under 5/24 to be able to open them just isn’t as important anymore.
We aren’t saying that 5/24 doesn’t matter anymore. Chase even changed a rule that did add back some importance to it, the ability to earn the bonus on both the Sapphire Preferred and the Chase Sapphire Reserve®. You’ll still need to be under 5/24 to collect the value from both cards.
The importance shifted from urgently staying under to being aware and managing it, which My10x can help give you that much-needed visibility into whether you’re under or over 5/24. Now, you’re planning a Chase window rather than starting with it as the primary focus. There’s still value to be had in Chase, but now you can still maximize that value even when starting with another bank.
Capital One is More Inquiry Sensitive
Capital One’s inquiry sensitivity used to mean that people just generally ignored Capital One. This was much easier when they had no transfer partners back in the day, but over the last few years Capital One Miles have become highly competitive with the likes of Chase and American Express.
The increased value from Capital One miles means it makes sense that you should get them. With their sensitivity to inquiries, it can be hard to get approved for Capital One cards after getting even moderately started on your points and miles journey.
As the card options have increased, and Capital One has made their points more valuable, they should be prioritized as an equal, which means they need some consideration to earn them. Without a long cooling off period after you get started, it can be hard to get in with Capital One. Starting with them avoids that issue.
Why the Venture Over Other Capital One Cards?
Capital One’s new family restrictions mean that the order you get them matters. Each card blocks your ability to get the bonus for all cards beneath it, so you want to start from the bottom and work your way up.
Compared to other cards:
- Capital One VentureOne Rewards Credit Card: the bonus is rather low, so unless they raise it, it’s OK to forfeit it.
- Capital One Venture X Rewards Credit Card: you can get it after the Venture, but not the other way around.
- Capital One Venture X Business: for someone new, this would be suggesting they get a high annual fee card and a business card, which isn’t typical for beginners. It’s also treated separately from these family restrictions.
The Venture hits the sweet spot of being a low annual fee card that doesn’t block you from getting the other Capital One cards with value.
Capital One Remains Simple
Capital One Venture:
- $95 annual fee
- 2X miles on all purchases
- 5X miles on hotels, vacation rentals and rental cars booked through Capital One Travel
Chase Sapphire Preferred:
- $95 annual fee
- 2X on all travel purchases except those that earn at a higher tier
- 3X on dining
- 3X points on vacation homes at eligible/top brands
- 3X on gas and EV charging
- 3X on top streaming services and online groceries (excluding Walmart, Target, and wholesale clubs)
- 5X on travel purchased through Chase Travel℠
- 1X on all other purchases
Does the CSP have higher earning potential? Yes. But for someone who is a beginner to points and miles, 2X on all purchases is just easier to understand. And, for many people, 2X will earn more than the blended higher rates available on the CSP.
The Trade Off
One area where Chase continues to outshine Capital One is in their transfer partners. Yes, Capital One has added a ton of value and many partners over the years. Chase still has better transfer partners that are beginner-friendly compared to Capital One. Capital One’s partners absolutely require understanding how partner award flights work whereas Chase has Southwest and United – domestic airlines most people are already familiar with.
Chase also has one of, if not the easiest beginner-friendly hotel partner: Hyatt. (Just note that Chase points now transfer to Hyatt at a 4:3 ratio with the CSP.)
What’s important to remember is that this is not a substitution, but rather a sequencing decision. We still recommend beginners pursue Chase cards and get into the Chase ecosystem early on in their points journey. Every Chase partner is still on the path, just sequenced differently than they were before, so that the opportunity available through Capital One is now maximized.
If you know you’ll only ever hold one or two cards and you want Hyatt, the CSP is still the right first card for you. If you’re looking to play the long game, our recommendation now is to start with the Venture and pick up the CSP when an elevated offer lands in your first 12 to 18 months. You’ll end up with both and a better CSP bonus than you’d have gotten in month one.
Putting It All Together
Looking at our reasons together:
- Chase’s lifetime restrictions mean we now feel that most people should wait for a limited-time elevated offer to get the CSP.
- Chase’s family restrictions on Inks and lifetime restrictions means they shut a tap that needed you to be under 5/24.
- Capital One’s increased value over the years and inquiry sensitivity necessitate being strategic about when you apply, and when you’re new, you’re in the best position you’ll ever be at in your points and miles journey.
- The Venture is the best starting point to get the value from Capital One’s program.
- Capital One remains simple in a world where most other cards are getting more complex.
Chase changed the rules, and those rules mean the strategy for their products is now to wait, rather than to have urgency. Since you can only earn the bonus once, it makes sense to wait for the best possible offer.
With less reason to need to start with Chase, we went and evaluated what card makes the most sense to recommend someone start with. Capital One does have a reason for urgency – with their inquiry sensitivity, starting with them puts you in the best position for approval. And the Venture is primed for new people in points and miles because of its approachable annual fee, lack of complexity, and ability to scale up in the ecosystem.
New to the world of points and miles? The Chase Sapphire Preferred® Card is the best card to start with.
With a bonus of Earn 75,000 bonus points after you spend $5,000 on purchases in the first 3 months from account opening. , 5x points on travel booked through the Chase TravelSM Portal and 3x points on restaurants, streaming services, and online groceries (excluding Target, Walmart, and wholesale clubs), this card truly cannot be beat for getting started!
once you spend $4,000 on purchases within 3 months from account opening.
Annual Fee: $95
after you spend $5,000 on purchases in the first 3 months from account opening.
Annual Fee: $95
Editors Note: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, hotel, airline, or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included within the post.
10xTravel is part of an affiliate sales network and receives compensation for sending traffic to partner sites, such as CreditCards.com. This site may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened. This compensation may impact how and where links appear on this site. This site does not include all financial companies or all available financial offers. Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. All values of Membership Rewards are assigned based on the assumption, experience and opinions of the 10xTravel team and represent an estimate and not an actual value of points. Estimated value is not a fixed value and may not be the typical value enjoyed by card members.
Editors Note: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, hotel, airline, or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included within the post.
bonus cash back
after you spend $8,000 on purchases in the first 4 months from account opening. Offer will end on 9/17/2026
earn 75K bonus miles miles
once you spend $4,000 on purchases within 3 months from account opening.
bonus points
after you spend $5,000 on purchases in the first 3 months from account opening.
Membership Rewards® Points
after you spend $8,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Welcome offers vary and you may not be eligible for an offer. Apply to know if you’re approved and find out your exact welcome offer amount – all with no credit score impact. If you’re approved and choose to accept the Card, your score may be impacted.